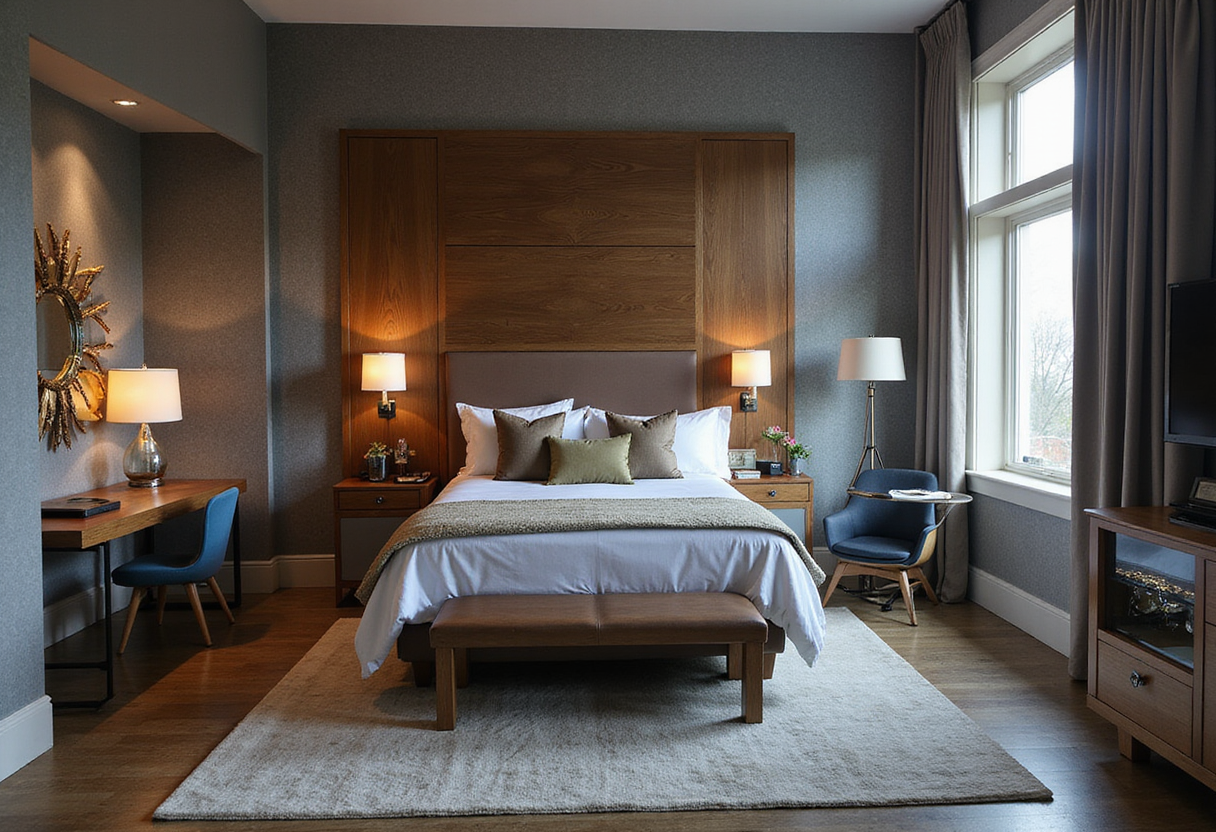
DiamondRock Pays $31M for Bellmoor Inn & Spa in Rehoboth Beach
DiamondRock acquired the 79-room Bellmoor Inn & Spa for $31M, or $392K per key, at an 8.6% cap rate, targeting a ~9.5% stabilized NOI yield after improvements.
DiamondRock Hospitality Company has acquired the fee simple interest in The Bellmoor Inn & Spa, a 79-room luxury resort in Rehoboth Beach, Delaware, for $31.0 million — roughly $392,000 per key. The company funded the deal entirely with cash on hand.
The purchase price implies an 8.6% capitalization rate on the hotel's trailing net operating income and a 10.4x multiple on hotel EBITDA, based on results for the twelve months ended August 2026. DiamondRock expects the transaction to have no material impact on fourth-quarter 2026 earnings.
What drives the yield thesis?
The real return case sits in the post-acquisition numbers. After DiamondRock applies its asset management initiatives and completes planned off-season capital improvements, management projects a stabilized hotel NOI yield of approximately 9.5% — roughly 90 basis points above the in-place cap rate.
That spread reflects a classic value-add playbook: buy an independent resort with strong in-place cash flow, invest during the shoulder season when disruption costs the least, and capture rate growth in a market where new competition cannot easily enter.
Why Rehoboth Beach?
CEO Jeffrey J. Donnelly framed the deal as a product of relationships and market fundamentals rather than a broad auction process.
"The acquisition of The Bellmoor reflects our track record of leveraging long-standing relationships to uncover compelling investment opportunities," Donnelly said in the announcement.
He pointed to Southern Delaware as "one of the East Coast's most attractive leisure lodging markets," citing affluent repeat visitors from the Northeast Corridor and significant barriers to new lodging supply. Those supply constraints underpin the pricing power behind the projected free cash flow growth.
Donnelly added: "Combined with our attractive acquisition basis and proven asset management platform, we believe these enduring fundamentals position The Bellmoor to generate meaningful free cash flow growth and long-term value for our shareholders."
How the deal fits DiamondRock's strategy
Key transaction metrics:
- Purchase price: $31.0 million for the fee simple interest
- Per-key basis: approximately $392,000
- Cap rate: 8.6% on trailing-twelve-month hotel NOI
- EBITDA multiple: 10.4x, twelve months ended August 2026
- Stabilized yield target: ~9.5% hotel NOI yield after capital improvements
- Financing: cash on hand; no material Q4 2026 earnings impact expected
The acquisition adds an independent, unbranded luxury asset to a portfolio strategy built on identifying operational upside rather than paying for flag-driven stability. The Bellmoor's cash flows from day one, and the off-season improvement timeline signals work concentrated in the lowest-occupancy window.
For a REIT buyer, the structure — all cash, fee simple, no near-term earnings drag — keeps balance-sheet flexibility intact while the asset management team closes the gap between the 8.6% entry cap rate and the 9.5% stabilized target. DiamondRock will look to replicate that spread as it continues sourcing off-market opportunities in supply-constrained leisure markets.
More from Elena Vasquez
Show full bio
News editor covering industry trends and analytics at The Pass Brief.
245 articles