DiamondRock buys Carmel Mission Inn for $73.25 million
DiamondRock paid $73.25 million for the 165-room Carmel Mission Inn, an off-market deal at an 8.1% cap rate, with upside tied to the 2027 U.S. Open and operating gains.
By Olivia Hart
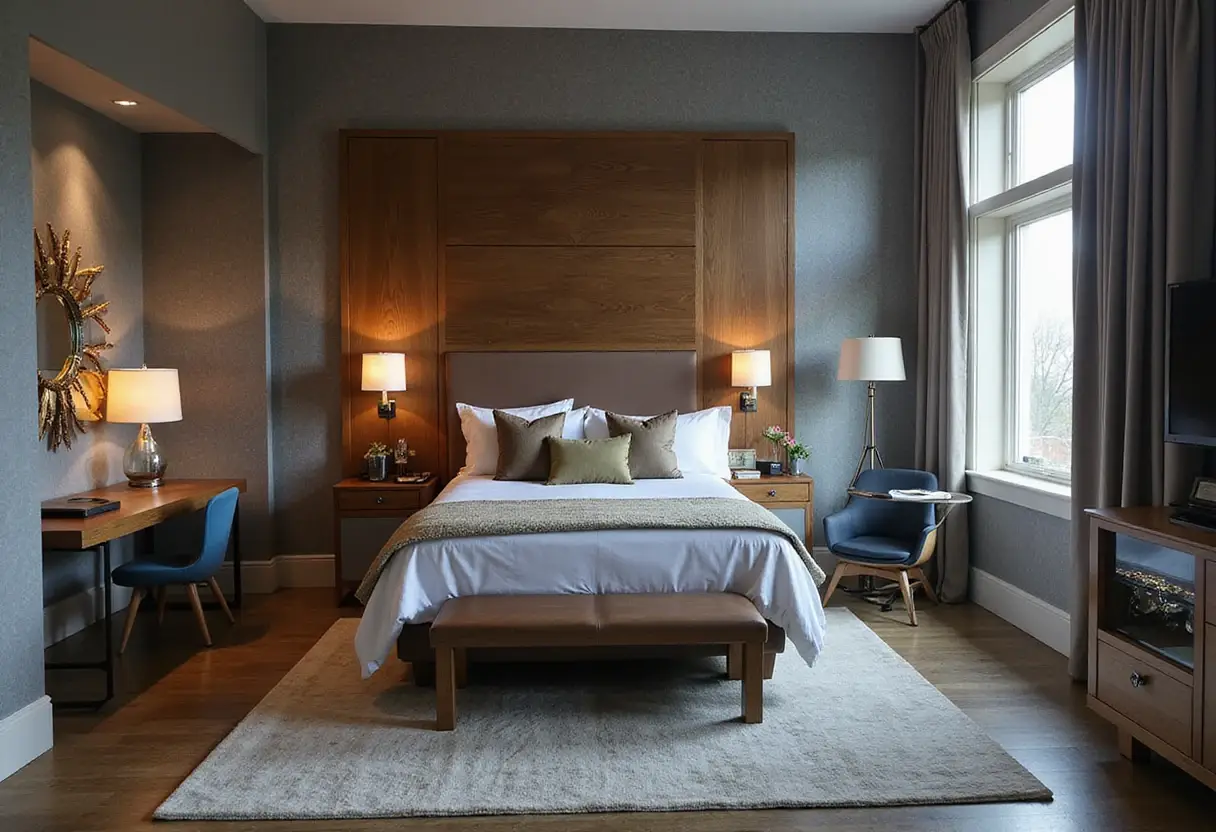
DiamondRock Hospitality Company paid $73.25 million for the 165-room Carmel Mission Inn, or $444,000 per key, in an off-market acquisition of the Carmel, California hotel’s fee-simple interest. The price equals 11.2 times trailing 12-month hotel EBITDA and an 8.1% capitalization rate on net operating income, based on results through October 2026.
DiamondRock funded the purchase with cash on hand, putting free cash flow into a hotel that already produces strong in-place cash flow. The acquisition should have no material impact on fourth-quarter 2026 earnings, leaving the property’s starting yield and planned operating improvements as the financial case.
How does the $73.25 million deal work?
The transaction gives DiamondRock ownership of the underlying real estate rather than a leasehold interest. For an owner, the 8.1% cap rate values the hotel’s trailing NOI against the purchase price, while the 11.2x EBITDA multiple shows what the buyer paid for its operating earnings.
“The acquisition puts our growing free cash flow to work at an attractive initial yield while providing a clear path to incremental earnings over time,” said Jeffrey J. Donnelly, chief executive officer of DiamondRock Hospitality Company. His statement separates the acquisition’s two economic mechanisms: an existing property yield and a plan to improve earnings without requiring substantial near-term capital investment.
Why does 165-room scale matter in Carmel?
At 165 rooms, Carmel Mission Inn is the second-largest hotel in Carmel. DiamondRock says that scale creates operating efficiencies that are difficult for the market’s smaller hotels and inns to achieve, particularly when a large room base already carries limited near-term capital needs.
The property sits one mile from Carmel-by-the-Sea and draws leisure demand across the Monterey Peninsula, including Pebble Beach, Big Sur and Monterey. Its location in one of California’s most supply-constrained coastal leisure markets, combined with current cash flow and modest capital requirements, supports the acquisition thesis.
Following a substantial renovation in 2021, the hotel requires only limited near-term capital investment. That matters because capital spending can reduce the cash available to support an 8.1% yield on NOI. A recently renovated room base instead lets DiamondRock concentrate on rates, distribution, demand and costs.
What will DiamondRock change?
DiamondRock plans to build on the hotel’s existing performance through five targeted asset-management initiatives:
- Revenue management
- Digital distribution
- Group demand
- Food and beverage profitability
- Operating efficiencies
Revenue management can affect room pricing and booking mix, while digital distribution can change the cost of reaching customers. Group sales can add occupied room nights, and operating efficiencies address the property’s broader cost base.
Food and beverage profitability carries a more specific margin question, but DiamondRock disclosed no sourcing changes, menu engineering or pricing actions. For now, improving departmental profit remains an objective rather than a detailed operating program.
What does this change for Carmel hospitality?
The ownership change gives DiamondRock direct control over the commercial and operating levers it has identified. For hotel guests and meeting planners, the practical result could include tighter digital booking, changes in room inventory and revisions to food-and-beverage offerings, although the announcement specifies no immediate service or menu changes.
The U.S. Open Golf Championship returns to Pebble Beach in 2027 and 2032, creating two scheduled opportunities to convert the hotel’s Carmel and Monterey Peninsula location into demand. DiamondRock has not quantified either event’s earnings contribution, so the events remain upside rather than booked revenue.
For other Carmel operators, the relevant question is whether Carmel Mission Inn can translate event-driven demand into higher NOI without allowing operating and food-and-beverage costs to absorb the gain. Its scale could intensify competition for both leisure guests and group business in a constrained market.
How does the acquisition fit DiamondRock’s portfolio?
DiamondRock, listed on Nasdaq as DRH, is a self-advised real estate investment trust with 35 premium hotels and resorts totaling 9,479 rooms. Its portfolio is geographically diversified and concentrated in leisure destinations and top gateway markets, with properties positioned for operation under global brand families and independent boutique lifestyle hotels.
DiamondRock describes the acquired Carmel property as independent and does not announce a franchise or management-contract conversion. The transaction therefore adds 165 rooms and an established leisure asset without introducing a disclosed chain conversion.
Ultimately, the acquisition’s value depends on execution after ownership changes. The next test is whether targeted revenue, distribution, group and food-and-beverage initiatives can lift earnings while limited capital needs protect the 8.1% starting yield, with the 2027 U.S. Open providing the first scheduled demand catalyst.
More from Olivia Hart
Show full bio
Staff writer covering regulation, policy and their impact on Restaurant and hotel operations at The Pass Brief.
757 articles